Debt Consolidation
We help you take back control of your repayments
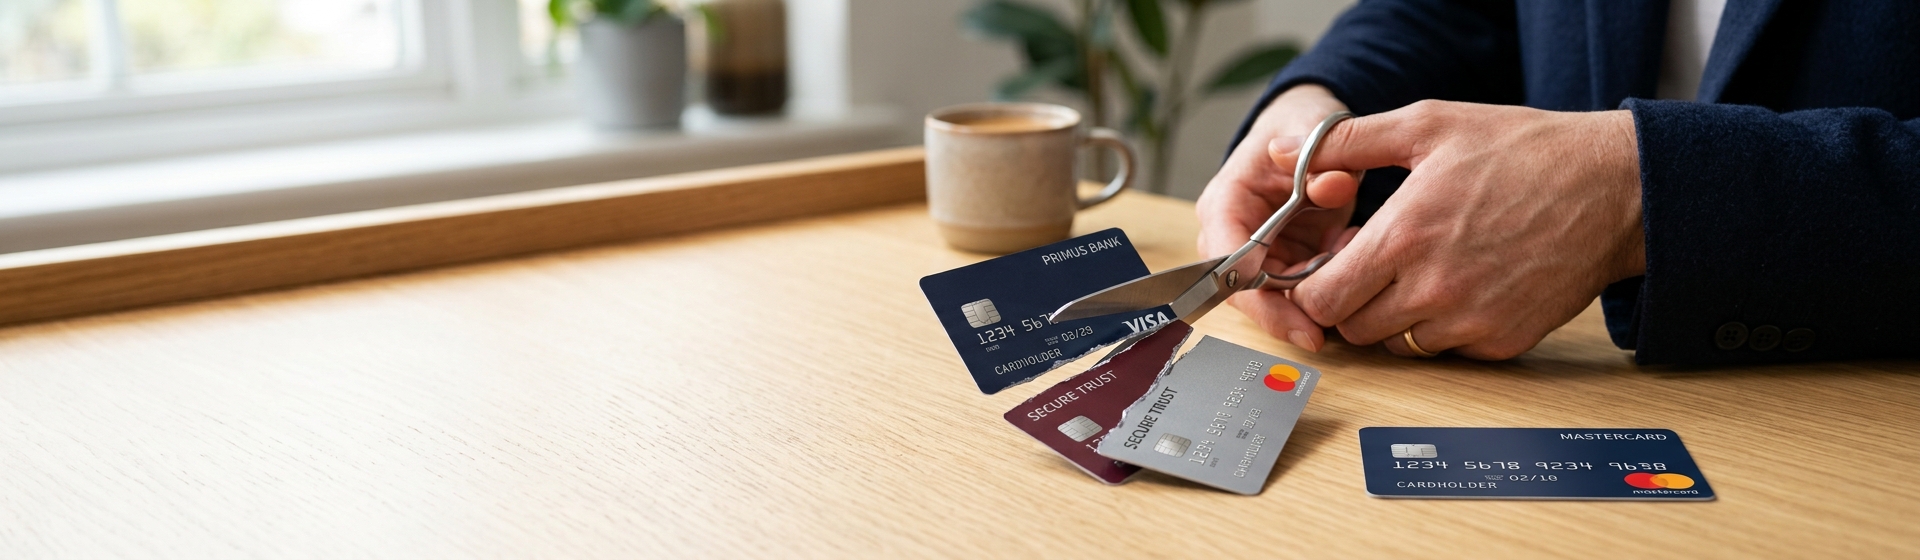
Juggling a home loan alongside credit cards, a car loan, or a personal loan adds up fast, both in cost and in mental load.
Consolidating debt is only the starting point. A lot of people assume rolling everything into one loan automatically saves money, and sometimes it doesn't, if it's structured the wrong way, you can end up paying more interest over the life of the loan simply because it's now stretched across a longer term. We work through that trade-off with you upfront, so you know exactly what you're signing up for, not just the lower monthly repayment, but the total cost over time.
From there, the focus shifts to paying the loan off faster, not just making it more manageable. That might mean a repayment strategy built around extra contributions, a structure that lets you chip away at the balance more aggressively once your cash flow improves, or a plan to revisit the loan again down the track as your situation changes.
This isn't a one and done service. It's a considered, ongoing strategy, built around where you actually want to end up and not just the immediate relief of fewer bills each month.
How We Help
Debt Review
Consolidation Structuring
Ongoing Support
Loan Repayment Calculator
See what your monthly repayments could look like based on your loan amount, interest rate and loan term.
Borrowing Capacity Calculator
Find out how much you may be able to borrow based on your income, expenses and current financial situation.
Frequently Asked
Read through our FAQ’s for added information. Have other questions? Contact our team today.
No, and we'll tell you plainly if it isn't. Sometimes a different repayment strategy makes more sense than consolidating, and we walk through the alternatives with you.
This depends on the structure chosen and the lender's processing times, but we move efficiently once your documents are in and keep you updated throughout.
In most cases yes, closing paid out accounts is part of the process and helps prevent the debt building up again.
Credit cards, personal loans, car loans, and in some cases tax debt can all be considered for consolidation, depending on your overall financial position.
Closing multiple accounts and opening a new facility can affect your score short term, but a manageable single repayment often improves your position over time. We explain what to expect before you proceed.
It depends on your goals and the total cost over time. Rolling short term debt into a long term mortgage can lower repayments now but cost more in total interest if not structured carefully. We walk through both options honestly.